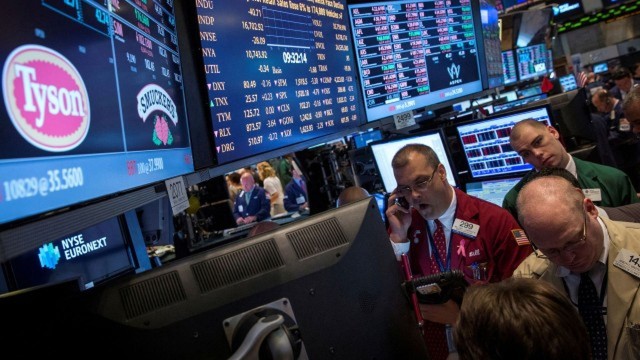
US stocks recovered from early losses on Thursday as a sharp rise in Treasury yields lost momentum, allowing investors to return to equities after several sessions of pressure. The S&P 500 rebounded from a two week low as government bond prices strengthened and yields moved lower, easing some of the concerns that had pushed markets into a defensive mood.
The early session had looked very different. Stocks opened under pressure after a series of economic indicators pointed to continued strength in the US economy, while signs of persistent price pressure raised fresh concerns about the Federal Reserve's next moves on interest rates.
The latest labor market figures added to those worries. The US Labor Department reported that initial claims for unemployment benefits fell to 197,000 in the latest week, below the 200,000 economists surveyed by Reuters had expected. The figure provided another indication that employers were continuing to retain workers despite the higher interest rate environment.
The claims data came one day before the government's closely watched monthly payrolls report. Investors were already looking toward Friday's employment figures for evidence about whether the labor market remains strong enough to support further interest rate increases.

Treasury yields reverse a sharp rise
The pressure on stocks intensified earlier in the session as Treasury yields continued climbing. The benchmark 10 year Treasury yield reached its highest level in 24 years, extending a rise that had already made September one of the most difficult periods for bond investors in recent history.
The 10 year Treasury note recorded its largest quarterly increase since 1994 as the third quarter ended. Rising yields can weigh on stocks because they increase borrowing costs for companies and make interest bearing assets more attractive relative to equities. Higher yields can also reduce the present value investors assign to future corporate earnings, particularly for growth and technology companies.
Fresh manufacturing data added to inflation concerns. The Institute for Supply Management reported that its manufacturing purchasing managers index slipped slightly to 54.5 last month from 54.6 in August. While the overall reading showed continued activity, the report also pointed to a rise in input prices, giving investors another reason to worry that inflation could prove difficult to contain.
That combination of strong economic activity and stubborn price pressure has become an important concern for financial markets. Investors have been trying to determine whether the Federal Reserve can eventually reduce rates or whether it will need to maintain tighter monetary policy for longer.
The direction of the bond market changed later in the day.
Treasury yields began to retreat as buyers returned to the market, and the decline accelerated after Federal Reserve Vice Chair Philip Jefferson indicated that policymakers could afford to be patient before raising interest rates again. The comments came after the central bank delivered a 25 basis point rate increase in September.
The two year Treasury yield, which is particularly sensitive to expectations for Federal Reserve policy, fell by almost 10 basis points. It was on track for its largest one day decline since August 2025.
The shift in bond yields provided some relief for stocks.
Scott Welch, chief investment officer at Certuity in Potomac, Maryland, said investors should not interpret the recent market moves as a sign that equities had entered a prolonged decline.
“Even though valuations have come down, the market's still not cheap, so I'm not bearish on the equity market,” Welch said. He added that he expected greater volatility in both stocks and bonds as investors adjusted to changing market conditions.
Welch described the current environment as a period of adjustment after several years in which investors had become accustomed to different interest rate and market conditions.
Major US indexes finish higher
By the closing bell, the main US stock indexes had recovered their early losses.
Preliminary figures showed the S&P 500 rising 17.28 points, or 0.23%, to finish at 7,668.82. The Nasdaq Composite gained 17.73 points, or 0.07%, to close at 26,871.60.
The Dow Jones Industrial Average added 29.84 points, or 0.06%, ending the session at 50,935.89.
The gains were modest, but the reversal was significant because stocks had been under pressure earlier as Treasury yields approached levels not seen in more than two decades.
Energy companies led the broader market higher.

Oil prices lift energy stocks
Oil prices added another layer to the inflation debate. Brent crude settled more than $4 a barrel higher after China suspended fuel exports, raising concerns about tighter supplies in global energy markets.
Higher oil prices can feed into inflation by increasing transportation and production costs across the economy. That creates a complicated backdrop for the Federal Reserve, which is attempting to keep inflation under control without unnecessarily weakening economic activity.
The increase in crude prices helped the S&P 500 energy sector gain almost 2%, making it the strongest performer among the index's 11 major sectors.
Technology stocks also contributed to the rebound. The technology sector rose nearly 1%, supported in part by strength in software companies following Accenture's latest results.
Accenture shares climbed to their highest intraday level since mid February after the consulting company projected full year revenue growth above analysts' expectations. The forecast offered investors another sign that corporate spending on technology services remains resilient despite elevated borrowing costs.
Micron Technology also finished higher. The semiconductor company benefited from a stronger than expected revenue forecast and $32 billion in customer commitments under supply agreements. The figures helped reinforce investor confidence in demand linked to artificial intelligence and advanced computing.
Investors reassess the Fed's next move
Expectations for another Federal Reserve rate increase have changed sharply during the week.
Softer than expected inflation data released on Wednesday reduced expectations that policymakers would raise rates at their October meeting. According to CME FedWatch, markets were pricing in a 28.2% probability of an increase of at least 25 basis points, down from 68.6% one week earlier.
That shift reflects the uncertainty facing investors. Economic activity remains firm, the labor market continues to show resilience and oil prices have moved higher. At the same time, recent inflation figures have reduced some of the pressure for another immediate rate increase.
Federal Reserve officials have also offered differing views on what should happen next.
After Jefferson's remarks, Minneapolis Federal Reserve President Neel Kashkari said he expects the central bank will need to raise interest rates further to restrain the economy as policymakers look toward 2027. Kashkari, however, said he was not certain whether the next increase should come at the October meeting.
Those differences illustrate the challenge confronting investors as they assess the path for monetary policy. A strong economy can support corporate earnings and stock prices, but persistent inflation can keep interest rates higher for longer. Falling Treasury yields provided some relief on Thursday, yet markets remain highly sensitive to each new employment, inflation and Federal Reserve signal.
With the monthly payrolls report due Friday, investors now have another major piece of economic data to digest. Will the jobs figures reinforce expectations for steady growth, or change the market's view of the Federal Reserve's next rate decision?