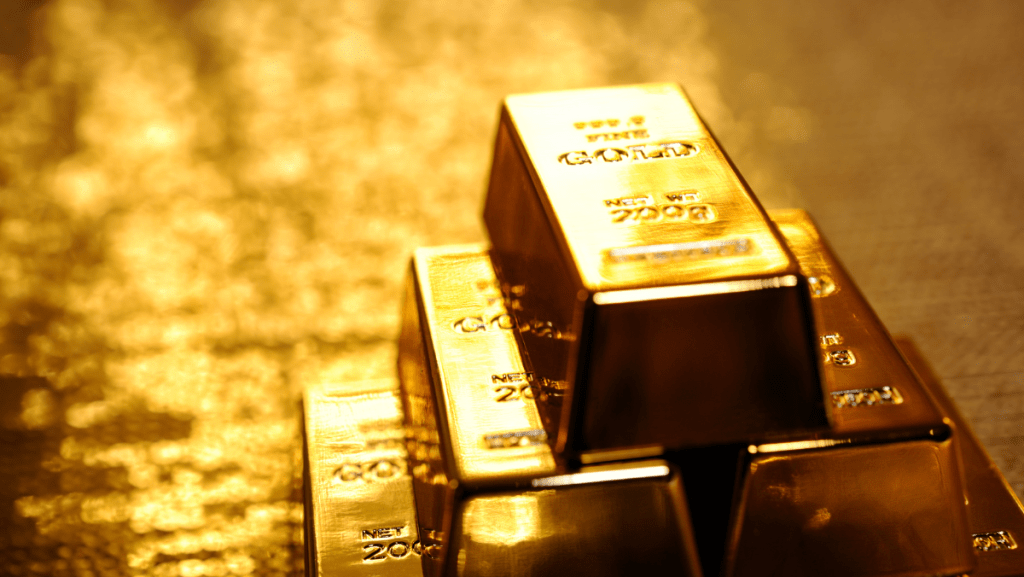
China’s net gold imports through Hong Kong increased by more than 4 percent in August, reflecting continued demand for bullion from investors as China’s lower interest rates reduced the appeal of some traditional investments.
The world’s largest gold consuming market imported 58.491 metric tons of gold on a net basis through Hong Kong during August, compared with 56.193 tons in July, according to data from the Hong Kong Census and Statistics Department released Thursday.
The increase came as Chinese investors continued to accumulate gold despite a sharp rise in bullion prices during the year. Demand has been supported by investors looking for alternatives to property and equities, while relatively low Chinese interest rates have reduced the income that can be earned from other assets.
Ole Hansen, head of commodity strategy at Saxo Bank, said Chinese investors were continuing to add gold as an alternative to property and stocks.
The difference between Chinese and overseas interest rate conditions has also influenced the calculation for gold investors. Gold does not generate interest income, which can make it less appealing when interest rates and bond yields rise. In China, however, short term and long term yields have remained significantly lower than in many other major markets.
That reduces the income investors give up by holding bullion instead of interest bearing assets.
Total imports also increase
China’s total gold imports through Hong Kong reached 77.137 tons in August, up from 75.457 tons in July. That represented an increase of more than 2 percent from the previous month.
The distinction between total and net imports is important because gross shipments include gold that may later be exported, while net imports provide a clearer indication of the amount entering China through the Hong Kong channel after accounting for outward shipments.
Hong Kong remains an important route for gold entering the mainland, but the monthly figures do not capture all Chinese gold purchases.
China also receives bullion through other trading centres, including Shanghai and Beijing. As a result, Hong Kong customs data cannot by itself provide a complete measure of national gold demand.
The August figures nevertheless add to evidence that Chinese buyers have continued to participate actively in the bullion market even after prices moved substantially higher.
Central bank extends buying streak
China’s central bank has also remained active in the gold market.
The People’s Bank of China increased its gold holdings for a sixth consecutive month in August, adding the largest amount of bullion to its reserves since October 2023, according to official data released earlier this month.
The August purchase extended the central bank’s gold buying streak to 22 consecutive months.
The continued purchases have attracted attention because they have taken place during a period when gold prices have climbed sharply. Central banks generally consider a range of factors when managing reserves, including diversification, liquidity and exposure to different forms of financial assets.
Rhona O’Connell, head of market analysis at StoneX, said official figures may not show the full amount of gold held by Chinese authorities.
She pointed to historical differences between reported holdings and figures recorded through International Monetary Fund data, saying the published People’s Bank of China holdings may not represent everything held officially.
That leaves some uncertainty over the full scale of China's official gold position.
Investors turn to bullion as yields remain low
Gold's appeal in China has also been shaped by the country's interest rate environment.
Unlike bonds, deposits or other interest bearing assets, gold does not pay a regular return. When borrowing costs and bond yields rise, investors typically face a higher opportunity cost when holding bullion because they give up potential interest income.
The calculation can look different when yields remain comparatively low.
Chinese investors have also faced uncertainty in the property market and shifting conditions in domestic equities. Gold provides another way to hold an asset outside those markets.
Hansen said the contrast between China and other major economies had reduced the opportunity cost associated with holding gold for Chinese investors.
This factor has become particularly relevant as global bond yields have risen in some markets. Investors elsewhere have had to weigh the appeal of higher fixed income returns against the possibility of further interest rate changes.
China's lower yield environment creates a different set of incentives.
The result has been continued interest in bullion from both private investors and the central bank, even as the price of gold has moved through elevated levels.
Gold records strong August before September pullback
Gold prices also posted a significant gain in August.
Spot gold rose more than 10 percent during the month, marking its strongest monthly advance since January. A weaker US dollar provided support, making dollar priced gold less expensive for buyers using other currencies.
Market expectations around US monetary policy also influenced trading.
The outlook changed in September as signals from the US Federal Reserve were interpreted as more supportive of higher interest rates. Those expectations contributed to a decline in gold prices, with spot bullion falling more than 4 percent so far this month.
Higher interest rates can weigh on gold because bullion produces no interest income. When investors expect rates to remain high, assets offering yields can become more attractive relative to precious metals.
The recent price movement therefore illustrates the competing forces affecting the market. Chinese demand has remained firm, while global monetary policy expectations have created pressure on prices.
Hong Kong remains an important trading route
The latest import figures also demonstrate the importance of Hong Kong in China's gold trade.
The city's customs data provides a regular indication of bullion flows into the mainland, although it must be viewed alongside imports through other Chinese cities.
Shanghai is particularly important to China's domestic gold market, while Beijing also handles bullion imports. Looking at Hong Kong figures alone can therefore produce an incomplete picture of overall Chinese demand.
Even so, the rise in August net imports provides another data point for analysts tracking physical demand.
Physical buying can have a different effect on the gold market from speculative trading in futures and other financial instruments. When consumers, investors and institutions purchase physical bullion, the metal moves through supply chains involving refiners, banks, dealers and exchanges.
China's position as the world's largest gold consumer means changes in its buying patterns are closely followed by international markets.
Central bank demand adds another layer
The People's Bank of China's continued purchases have provided another source of demand.
The central bank's 22 month buying streak shows that the accumulation of bullion has extended well beyond a short term market move. The latest increase in reserves also came during a period of elevated prices.
The reasons behind central bank gold purchases can differ from those influencing private investors. Reserve managers may consider diversification, international liquidity and the composition of official assets, while individual investors are more likely to focus on wealth preservation, price movements and alternatives to domestic financial markets.
The two forms of demand can nevertheless affect the same physical market.
China's official purchases have therefore become an important part of the wider gold market story, particularly as other economic and monetary factors continue to shift.
What the latest figures mean for China's gold demand
The August Hong Kong data points to continued Chinese interest in gold despite the metal's strong performance earlier in the year.
Net imports rose from 56.193 tons in July to 58.491 tons in August, while total imports increased from 75.457 tons to 77.137 tons.
Those numbers do not represent all gold entering China, since other ports and trading centres also handle bullion. They also cannot establish exactly why every investor purchased gold.
They do, however, show that demand through one of China's major import channels increased during a month when global gold prices posted their strongest monthly gain since January.
The combination of private investment demand, central bank purchases and relatively low Chinese yields has kept attention on China's role in the international gold market.
For investors and analysts tracking the next stage of the bullion rally, the key figures to watch will include China's monthly reserve purchases, physical import data from Hong Kong and other entry points, domestic demand and changes in global interest rate expectations.
Will China's continued gold buying remain strong if global interest rates stay higher for longer?